Meet the average American family.
Every screenshot on this site is The Silo running on a demonstration household built from median U.S. figures. Not a real member's data. Here is that household in full, and then a year in the life of a family of four, check-in by check-in.
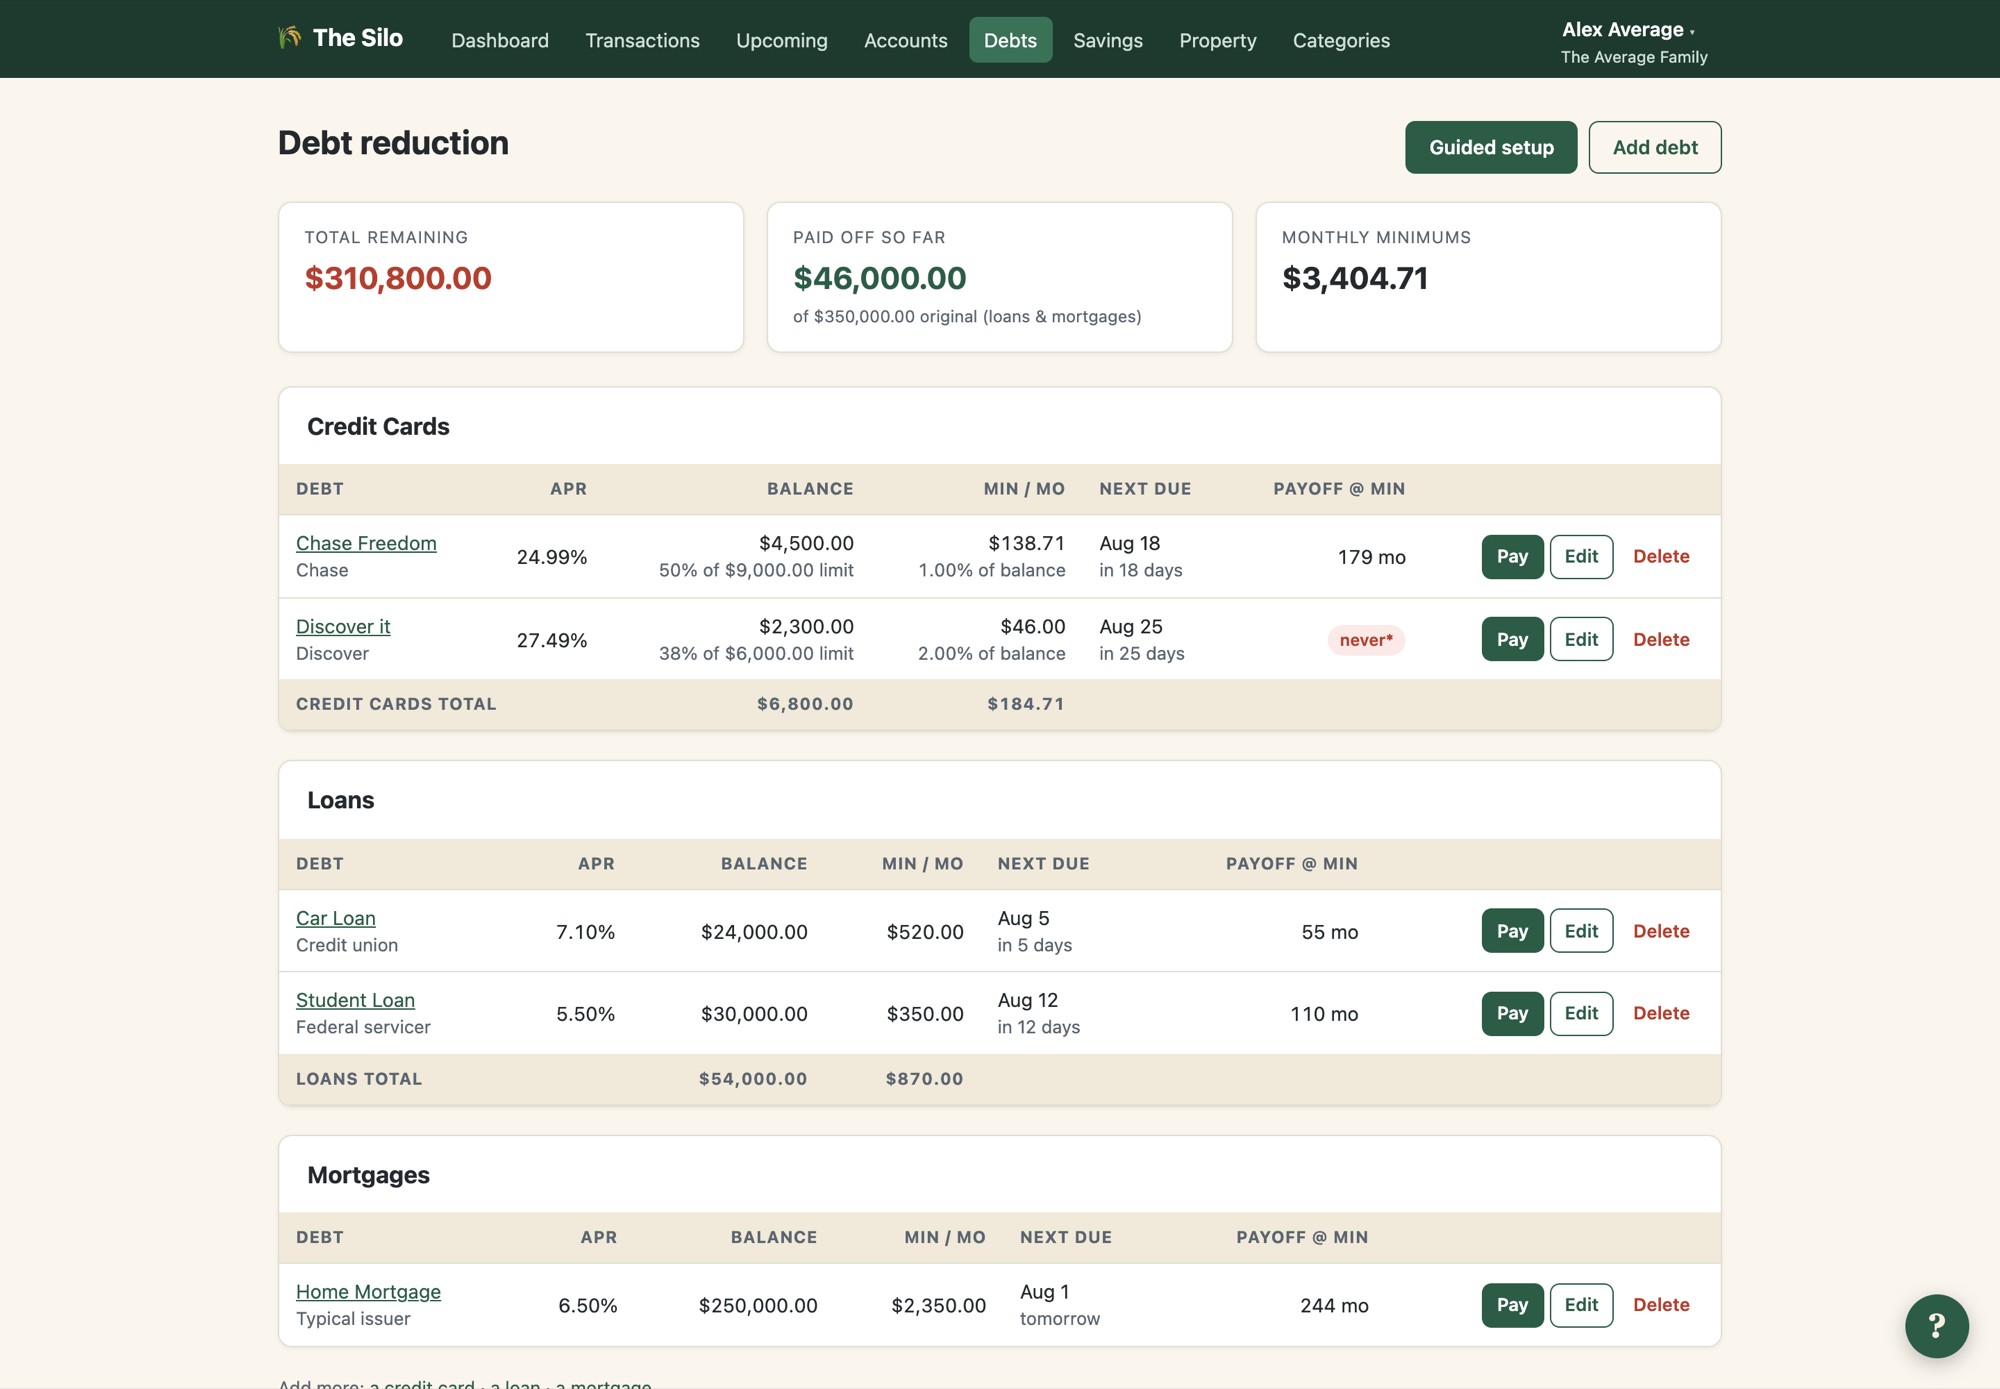
Total debt
$310,800
a mortgage, a car, student loans, two cards
Monthly minimums
$3,405
what the lenders ask for, every month
Debt-free at minimums
Mar 2040
162 months from now
Every debt, one page
The number the lender never puts in bold.
APRs, balances, minimums, due dates, and how long each debt takes at the minimum. The Discover card, at a 2% minimum, says "never." That is not a bug. That is the card working as designed.
Payoff @ min: the car takes 55 months, the Chase card 179, the Discover card never. Run the Discover card yourself in the free calculator.
The plan
What $200 a month does.
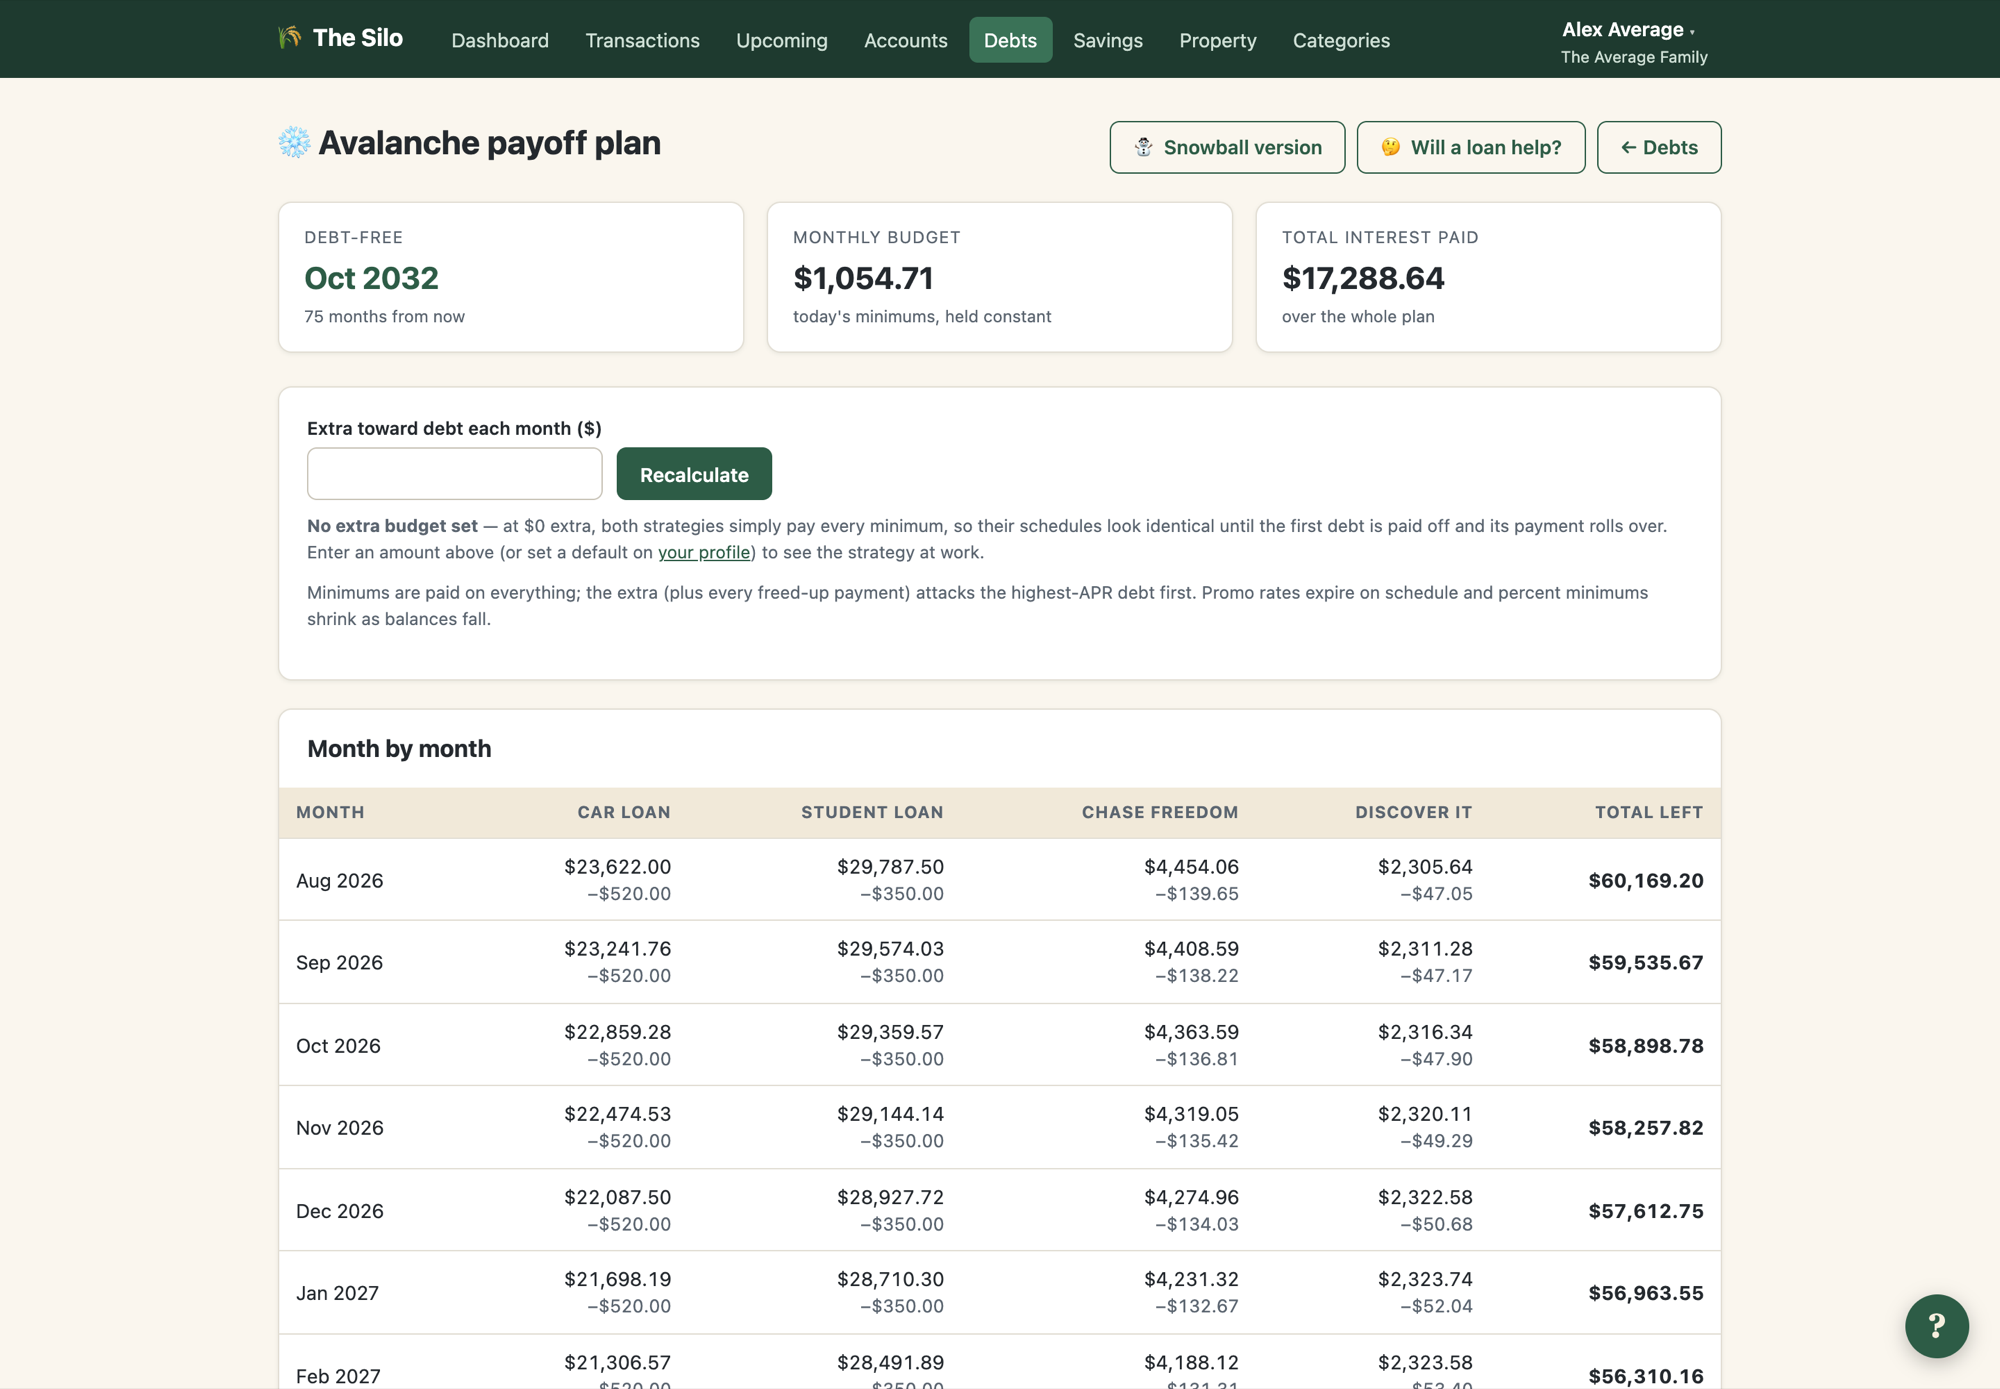
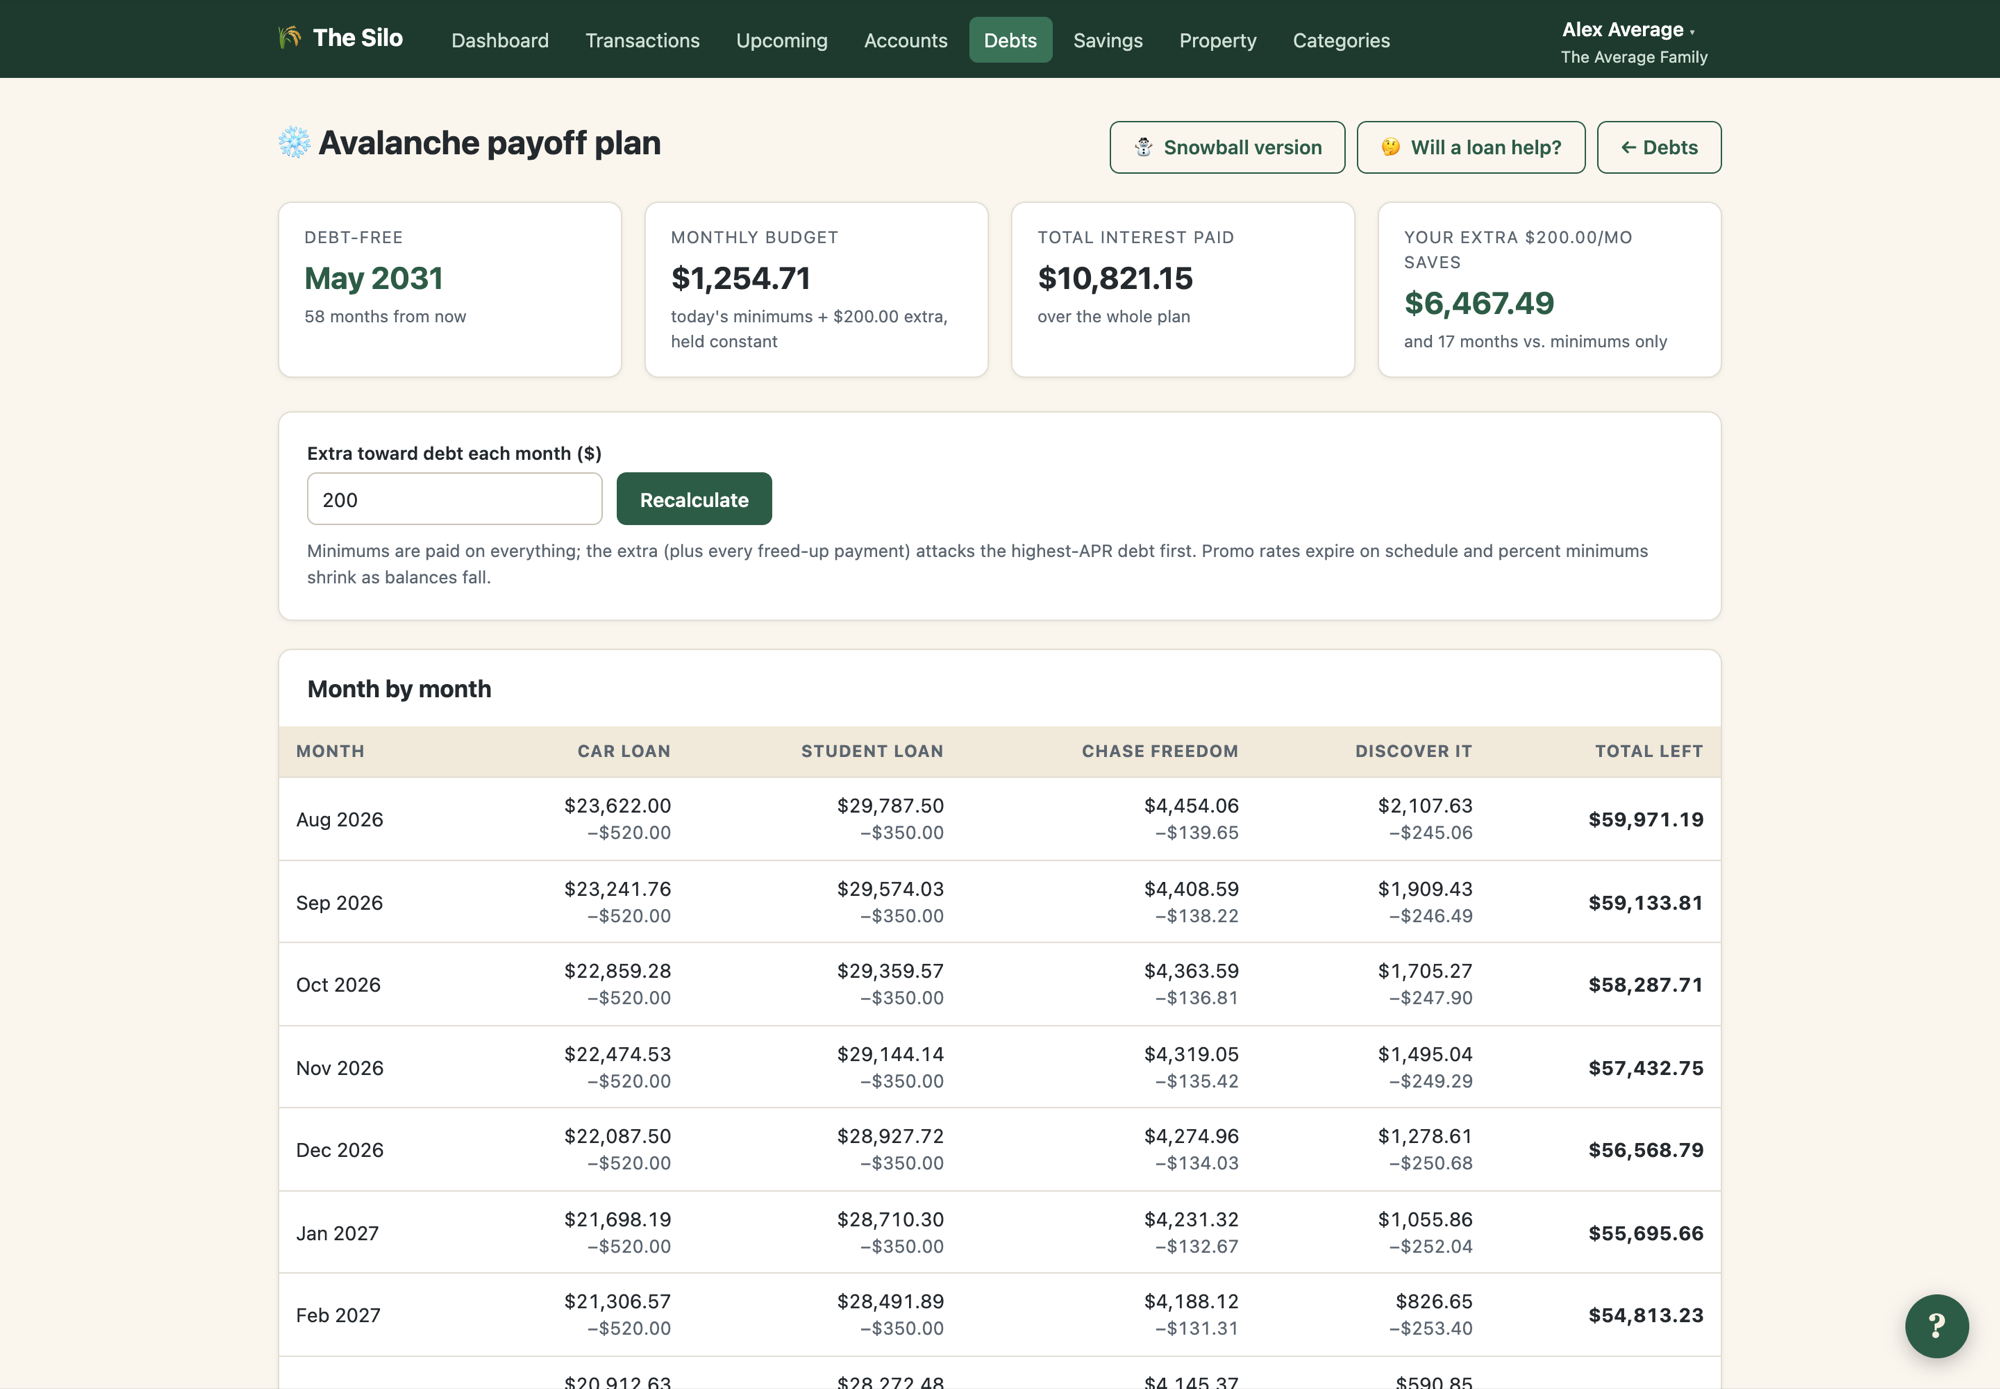
Set the mortgage aside and aim the plan at the consumer debt. The avalanche pays every minimum, sends the extra at the highest rate first, and rolls each cleared payment onto the next debt.
Minimums only
Consumer debt gone Oct 2032 · $17,289 in interest.
$200/mo extra
Gone May 2031 · $10,821 in interest.
$200 a month buys back 17 months
and keeps $6,467 away from the lenders.
Real issuer minimum formulas, promo expirations on schedule, and never a dollar the month doesn't have.
Try it with your own numbers.
One card, one balance, one APR. The free calculator runs your issuer's real minimum-payment formula and tells you the honest answer. No signup.
Open the calculator
A year on Larkspur Lane
The Whitakers are the second demo household: four logins, a joint account, two paychecks, a mortgage with twenty-seven years left, and one truck that met the back of a Camry on I-85. Every figure below is a balance from that household's ledger as of September 13.
Dana, 44Office manager at Bright Smiles Dental. Does the groceries, the Target runs, the kids' everything. Pottery on Tuesday nights. Owns the household in The Silo.
Marcus, 46Electrician with Keller Electric. Fixes what breaks, pays the utilities, and keeps two boxes of baseball cards and 300 records he values at $6,000. Nobody else does.
Nora, 17Senior. Trumpet in the marching band, club soccer in spring. Saving for a used car that starts. Spent the summer hauling mulch at Green Thumb Nursery.
Eli, 12Seventh grade. Theater kid, cast in Into the Woods Jr. Cross country in the fall because his sister said so. Wanted the new Zelda on allowance alone. Mom said allowance alone.
What a normal month looks like
Dana clears $1,890 every other Friday. Marcus clears $2,050. The day after each check a fixed share moves to the joint account, $1,000 from Dana and $1,400 from Marcus, and the joint account pays for the house.
Joint account · recurring
| Mortgage, 1st (P&I $1,909 + escrow $620) | 2,529.00 |
| Electric, 8th (Jan 178 → Aug 239) | ~165.00 |
| Natural gas, 10th (Jan 132 → Jul 29) | ~70.00 |
| Water & sewer (74 → 79 in July) | 79.00 |
| Internet (79.99 → 89.99 in June) | 89.99 |
| Cell phones, family plan | 170.00 |
| Auto insurance (262 → 298 in August) | 298.00 |
| Life insurance, term, both | 52.00 |
| Netflix (17.99 → 19.99 in April) | 19.99 |
| Spotify Family (19.99 → 21.99 in July) | 21.99 |
| Disney+ (canceled June 1) | — |
| YMCA family membership | 89.00 |
| Costco run, 15th | ~190.00 |
| Emergency fund sweep, 16th | 300.00 |
| Allowances, Fridays (Nora $25, Eli $15) | ~173.00 |
| Fixed, before groceries and the kids | ~4,250.00 |
What each of them keeps pays their own debts: Dana's CR-V at $455, her student loan at $185, and $300 and $275 to two cards. Marcus's student loan at $140, the Home Depot card, and Capital One at $175.
Debts · balances on January 1
| Home mortgage, joint, 27 years left | 6.25% · 268,400.00 |
| Honda CR-V loan (Dana) | 6.90% · 18,900.00 |
| Student loan (Dana) | 5.05% · 14,200.00 |
| Student loan (Marcus) | 4.50% · 9,800.00 |
| Chase Sapphire Preferred (Dana) | 24.24% · 3,800.00 |
| Capital One Quicksilver (Marcus) | 26.49% · 2,900.00 |
| Target RedCard (Dana) | 27.90% · 2,150.00 |
| Home Depot card (Marcus) | 29.99% · 1,650.00 |
| Total | 321,800.00 |
Where the everyday money goes
Groceries are the biggest everyday line, around $212 a week in January and creeping toward $220 by August. Inflation shows up here first, about a quarter of a percent a month. The Target card is where the kids' life happens. Marcus buys gas station coffee every workday, the truck drinks $72 a week, and dinner out is every other Friday on the Chase card.
Everyday averages · June through August, per month
| Groceries | 1,124.24 |
| Gas, two vehicles | 547.27 |
| Shopping, mostly Target | 308.23 |
| Dinner out | 265.84 |
| Lunch | 239.96 |
| Coffee | 232.48 |
| Everything else: music, hobbies, entertainment, snacks, personal care, streaming | ~395.00 |
| All everyday categories, before bills and debt | ~3,113.00 |
February: the water heater
On February 3 the water heater died during Nora's shower. Marcus put the new one on the Home Depot card for $1,289 and paid the plumber $425 from the joint account.
Check-in · February 3
| Home Depot card, February 2 | 1,650.00 |
| Home Depot card, February 3 | 2,988.18 |
He raised his Home Depot payment from $120 to $200 starting in March. The debts page had shown him the payoff-at-minimum column and he did not like the word in it.
March: the closest call, and the refund
The joint account bottomed out on March 6 at $503.93. Nothing bounced. The upcoming view had flagged the dip two weeks earlier, and Dana had already moved her Chase payment to the 18th.
Check-in · March
| Joint checking, March 6 (low point of the year) | 503.93 |
| Federal refund, March 20 | +2,140.00 |
| Moved to emergency fund, March 21 | 1,500.00 |
| Emergency fund, March 31 | 8,600.00 |
May 9: the truck
Marcus was rear-ended on I-85 on the way to a job. He was fine, mostly. The truck was not. Urgent care was a $150 copay. The body shop wanted the $1,000 deductible up front, and Marcus was in a rental for nine days.
Check-in · May 13 and 14
| Joint checking, May 13 | 2,011.95 |
| Deductible to the body shop, May 14 | −1,000.00 |
| Drawn from emergency fund, May 14 | +1,400.00 |
| Joint checking, May 14 | 2,391.96 |
| Emergency fund, May 14 | 7,500.00 |
| Capital One, May 31 (rental on it) | 3,143.90 |
Dana made the transfer the same afternoon, before the deductible cleared, because the upcoming view showed the joint account going to $1,011 with the phone bill and a Costco run still ahead of the next paycheck. That is the whole reason the fund existed. Out of pocket for the accident, all in: $1,931, plus a truck worth $600 less and an insurance premium up 14% at the August renewal.
Summer: how they dug out
Four things, none of them dramatic. They canceled Disney+. Dana paused her pottery membership for three months. The emergency fund sweep dropped from $300 to $150 for the summer so the joint account could breathe. Marcus kept the Home Depot payment at $200. Nora started at the nursery June 1 and moved $200 of every $310 check into the car fund. Eli bought the new Zelda on release day, June 5, after hitting $69.99 in March and being made to wait for the game to exist.
Check-in · June 30
| Joint checking | 3,945.01 |
| Family emergency fund | 7,950.00 |
| Nora car fund | 2,000.00 |
| Eli savings, after the game | 217.00 |
August: school, tires, and the renewal
Marching band fee $300. Cross country fee and shoes $172. Back-to-school at Target $238. School fees and lunch accounts $190. Insurance renewed at $298, and the letter mentioned "a recent claim." Then the CR-V needed four tires: $642 on the Chase card, because that is where big things go.
Check-in · August 31
| Joint checking | 3,979.38 |
| Family emergency fund | 8,250.00 |
| Nora car fund | 2,890.00 |
| Chase Sapphire (tires, cabin, dinners, interest) | 4,872.62 |
| Target RedCard | 2,863.88 |
| Capital One | 3,078.89 |
| Home Depot card | 2,846.87 |
September 13: where they stand
The mortgage has dropped $4,697 since January. Of the $22,761 paid on it, $12,484 was interest and $5,580 was escrow. The emergency fund is $2,050 higher than it started, after absorbing a truck. Nora's car fund is at $2,910, 48% of the way to $6,000, with driver's ed paid for.
Check-in · September 13, the dashboard
| Net worth | 255,100.27 |
| Cash on hand, all bank accounts | 24,358.32 |
| Total debt | 315,422.94 |
| Credit card debt, four cards | 13,863.03 |
| Card interest paid since January | 2,060.25 |
| Payoff date | — |
That last line is the one that matters. The cards started the year at $10,500 and stand at $13,863, and the Whitakers paid about $950 a month toward them the whole time. The water heater, the rental, the tires and $2,060 of interest went on faster than the payments came off.
At today's minimums the cards never reach zero.
The plan says so: $51 a month short.
Interest adds $797 a month back and the everyday spending landing on the cards adds another $1,127. Paying $200 more does not fix it, because the charges keep growing. The Silo's suggestion is the unglamorous one: stop the everyday spending from landing on the cards. That is October's job.
The accident was survivable because they had a fund and a forecast that told them, two weeks early, exactly which day would hurt. The cards are the slower problem, and they only saw it because The Silo refused to print a payoff date it didn't believe.
Your household is not the average one.
Type in your own accounts, cards and loans and The Silo gives you a real debt-free date, the day an account will run short, and the number to bring to the raise conversation. No bank linking. You enter the numbers, you keep the data.
Set up a household. It's free.